If your tax strategy is built on the assumption that rates will be the same, or lower, in the future, it is worth looking at what history actually shows.
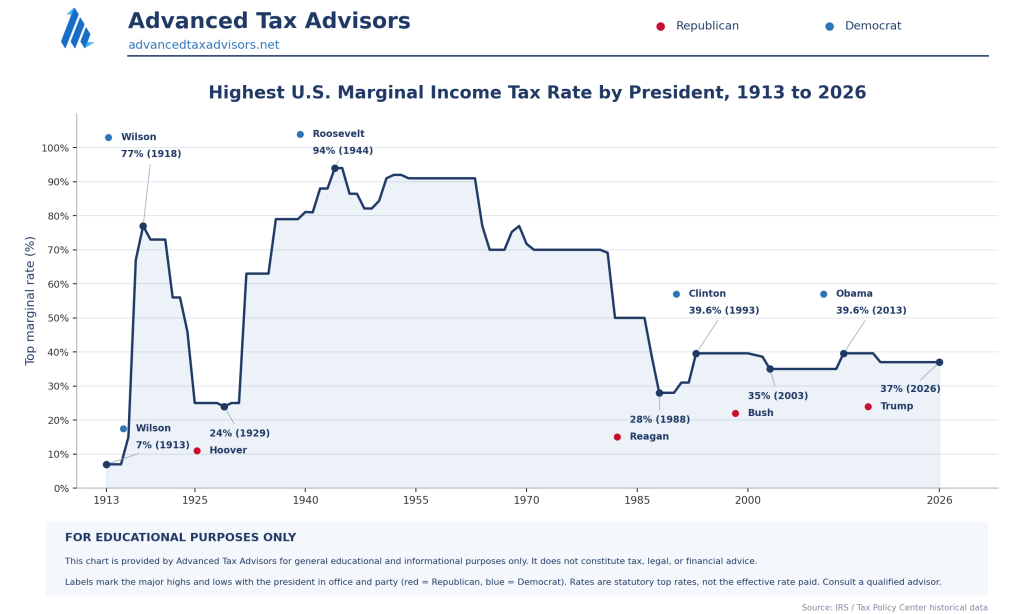
The top U.S. marginal income tax rate has been as low as 7% and as high as 94%. Not in different countries. Not in a textbook example. Right here, in the same country where you are building your business and planning your retirement.
That history does not just make for an interesting conversation. It changes how you think about tax deferral, Roth conversions, entity structure, and every decision where the timing of taxation matters.

A Brief History of U.S. Income Tax Rates
The U.S. federal income tax was established in 1913, following ratification of the 16th Amendment. In that first year, the top rate was 7%. Within five years, it had climbed to 77%.
What happened in between? World War I.
That is not a coincidence. Tax rates have almost never changed in isolation. Every major shift in the top marginal rate has been driven by something bigger: a war, an economic crisis, a political shift, or mounting national debt. The rate itself is just the symptom. The cause is always the environment.
1913 to 1920: The War Premium
The income tax started modest. The government needed to fund an unprecedented military buildup and an overseas war, and the tax code became the primary funding mechanism. By 1918, the top marginal rate had reached 77%. High earners at the time saw their effective burden multiply in under a decade, with little warning and even less recourse.
After the war ended, rates came down. But the precedent had been set. When the country needed money, the tax code was the tool.
1929 to 1945: Depression, Recovery, and Another War
The 1920s brought meaningful rate reductions. By 1929, the top rate had fallen to 24%. Then the Great Depression hit.
Rates climbed again through the 1930s as the federal government funded relief programs and economic recovery. By the time World War II was fully underway, the top marginal rate had reached 94% in 1944 under Franklin D. Roosevelt. That is not a typo. For every dollar earned above a certain threshold, the government claimed 94 cents.
Wartime spending and social safety net expansion required revenue at a scale the country had never seen. The tax code delivered it.
1945 to 1980: The High-Rate Era Most People Have Forgotten
After World War II ended, rates did not come back down to pre-war levels. They stayed high, in the 70 to 91 percent range, for decades.
The post-war economic boom coincided with some of the highest marginal tax rates in U.S. history. The government was funding the Korean War, the interstate highway system, the space program, Social Security expansion, Medicare, Medicaid, and the ongoing costs of maintaining a global military presence.
If you were a high earner in 1960, your top marginal rate was 91%. That was not a temporary emergency measure. It was policy for over 30 years.
1981 to 2000: The Reagan Cuts and Their Limits
Ronald Reagan campaigned on reducing the tax burden and delivered. The Economic Recovery Tax Act of 1981 began a sustained reduction in top marginal rates. The Tax Reform Act of 1986 brought the top rate down to 28%, the lowest it had been since the 1920s.
It did not hold. By 1993, under President Clinton, the top rate was back up to 39.6% to address a growing federal deficit. What the Reagan era demonstrated was not that rates stay low once cut. It demonstrated that rates respond to fiscal reality. When the budget required it, Congress raised them again.
2001 to Present: The Modern Rate Environment
The Bush tax cuts of 2001 and 2003 reduced the top rate to 35%. The Obama administration raised it back to 39.6% in 2013. The Tax Cuts and Jobs Act of 2017 brought it down to 37%, where it sits as of 2026.
That is a historically moderate rate. The more useful question is what conditions have caused rates to move, and whether any of those conditions exist today.
Why Assuming Rates Stay Low Is a Bet, Not a Plan
The current top marginal rate of 37% sits in one of the lower ranges in modern U.S. history. Compared to the 70%, 80%, and 90%-plus rates that persisted for decades, today is relatively favorable.
That does not mean rates are going up tomorrow. But here is what every serious high-earner should sit with.
The U.S. national debt has grown significantly in recent decades. Defense spending, entitlement programs, and interest on existing debt create structural pressure on the federal budget. These are not partisan observations. They are fiscal math.
Every time the country has faced a sustained need for increased revenue, the income tax code has been one of the primary tools. There is no credible historical argument that this time is categorically different.
Most tax deferral strategies are built on an implicit assumption: that future rates will be equal to or lower than today’s. Traditional 401(k) contributions, traditional IRA deductions, and other deferral vehicles all follow this logic. You skip the tax now. You pay it later. The bet is that “later” will be cheaper.
That bet may be right. But it is still a bet. And the last 100 years of U.S. tax history is the track record you are betting against.
What a Rate-Aware Tax Strategy Actually Looks Like
A proactive tax strategy does not assume rates will go up. It does not assume they will stay the same either. It accounts for both possibilities and builds flexibility into your financial structure.
Here are the questions we work through with clients.
Are You Carrying Unnecessary Deferral Risk?
Maxing out traditional pre-tax accounts feels like a win in the short term. But if rates rise significantly before you draw from those accounts, the deferred liability grows with them. Roth conversions and Roth contribution strategies are worth modeling, especially in years when your taxable income is lower than usual.
Is Your Entity Structure Locking In Your Exposure?
Business owners have more control over when and how income is recognized than most people realize. The right entity structure (whether that is an S-Corporation, a holding company arrangement, or something else) affects not just this year’s tax bill but your ability to respond to future rate changes. A structure that made sense at a 28% top rate may need revisiting at 37% and would need serious reconsideration at 45%.
Are You Using Current-Law Strategies While They Are Available?
Every favorable provision in the tax code has an expiration date, a repeal risk, or a phase-out threshold. Qualified Business Income deductions, accelerated depreciation, cost segregation, and retirement plan contribution limits are all worth maximizing under the rules that exist today, not the rules you hope will still exist in five years.
Do You Have Assets in More Than One Tax Bucket?
The most resilient strategies are not optimized for one scenario. They build flexibility across taxable, tax-deferred, and tax-free asset types. That means working with an advisor who tracks the legislative environment year-round, not just during filing season.
The Bottom Line
Tax rates are not a permanent fixture. They are a policy instrument that has been used aggressively, repeatedly, and often with very little warning, to respond to the financial demands of the country at a given moment.
The current environment is moderate by historical standards. That is an opportunity worth acting on.
Every month without a tax plan is a month where decisions get made by default. In a rate environment that history shows can shift dramatically, default is an expensive position to hold.
Free Discovery Call
If you have been deferring taxes and assuming rates will cooperate, it may be time for a second look.
Book a free Discovery Call and we will walk through your current structure, your deferral exposure, and where there may be room to act while rates are where they are.
This content is for educational purposes only and does not constitute tax, legal, or financial advice. Results vary based on individual tax situations. Consult with a qualified tax professional before implementing any tax strategy.
Frequently Asked Questions
Will tax rates go up in the future?
No one can predict future tax rates with certainty. What history shows is that U.S. top marginal rates have changed dramatically in response to wars, economic crises, and fiscal pressure, rising as high as 94% in 1944. The current rate of 37% is moderate by historical standards, which is why many tax advisors recommend strategies that do not rely entirely on rates staying low.
What has been the highest U.S. income tax rate in history?
The highest top marginal income tax rate in U.S. history was 94%, reached in 1944 during World War II under President Franklin D. Roosevelt. This rate persisted at elevated levels well into the 1960s and 1970s.
Why do income tax rates change over time?
U.S. income tax rates have historically shifted in response to wars, economic downturns, deficit reduction efforts, and changes in political priorities. Rate changes are typically tied to the government’s need to increase or reduce federal revenue.
Is it better to pay taxes now or defer them to the future?
Whether to pay taxes now or defer them depends on your projected future tax rate, your retirement income, and the current legislative environment. Given that historical rates have risen significantly during periods of fiscal pressure, a thoughtful strategy often includes building tax-free assets alongside tax-deferred ones rather than relying entirely on deferral.
What is tax deferral risk?
Tax deferral risk is the possibility that the rate you pay when you eventually withdraw from deferred accounts will be higher than the rate at which you deferred. If rates rise before retirement, the deferred tax liability grows with them.
What strategies help protect against future tax rate increases?
Strategies worth considering include Roth conversions, Roth IRA and Roth 401(k) contributions, business income timing, entity restructuring, and maximizing current-law deductions like accelerated depreciation and Qualified Business Income deductions while they remain available. Results vary based on individual circumstances.